
You sell the stock that's up, keep the one that's down and call it patience.
Kahneman (2011) puts it as a coin flip: tails you lose $100, heads you win $150. The bet pays more than it costs on average and many people still find it unattractive. Losing $100 weighs more with them than winning $150.
By the end of this, you'll know why a possible loss often outweighs an equal gain and how to stop it deciding for you.
The meme treats every loss as if it could ruin you.
The advice is right for losses you cannot come back from: bankruptcy or a serious injury. Loss aversion puts the same extra weight on losses you could absorb easily, such as a small bet or a slow month. It also leaves out the losses that come from doing nothing, because those do not feel like losses at all.
Loss aversion does not only make change feel expensive. It makes staying put look free.
How it works
The leading account comes from prospect theory. Kahneman and Tversky (1979) proposed that people judge outcomes as gains or losses from a reference point (usually what they have now) rather than as final amounts of wealth. Below that point the value curve is steeper. A loss of a given size therefore registers more strongly than a gain of the same size.
How much more is less settled than the popular 'twice as much' line suggests. Brown and colleagues (2024) pooled 607 estimates from 150 articles and put the average loss aversion coefficient at about 1.96, most likely between 1.8 and 2.1. Single studies range widely around that average and the result depends on how the question is asked.
What produces the effect is also contested. Gal and Rucker (2018) reviewed the evidence and argued that many results credited to loss aversion are better explained by inertia: a preference for keeping things as they are, whether or not a change is framed as a loss. The 2024 meta-analysis reports a clear average effect. Losses usually weigh more than gains, by an amount that shifts with the stakes and the framing.
Knowing about it does not switch it off. The asymmetry acts on how a choice feels before you weigh it, which is why the countermeasure below changes the frame instead of relying on willpower.
Also shows up in
- Negotiation: what you give up looks larger than what you get. Both sides then ask more to make the trade than they would pay for it.
- Careers: the pay cut in a move to a better role feels larger than the same amount of future upside.
- Products: a team stops a test that shows a 2% drop in sign-ups but lets one that shows a 2% rise run to the end. A bad early result becomes a reason to stop and a good one a reason to continue. The asymmetry may then come from the stopping rule and not from the evidence.
Countermeasure
Run the Two-Sided Loss Ledger on any keep-or-change decision you have put off for more than two weeks. It matters most when the worst case of acting is one you could recover from within a year.
1. Write the loss of acting: name what you give up if you change, in money, time or standing.
2. Write the loss of not acting: name what you give up if you stay, in the same units and over the same period. This is usually the column that stays empty.
3. Check the stakes: if the worst case in either column is ruinous, treat it as a hard limit. First ask whether the risk can be reduced, delayed, insured or made reversible. If it cannot, do not trade it off against ordinary upside. Extra weight on that risk is caution rather than bias. A loss that cannot be undone but would not ruin you is not a hard limit. Weigh it in the ledger at its full size.
4. Widen the frame: treat this as one of many similar choices you will make, as a trader treats one position in a portfolio. Ask which rule you would want to follow across all of them.
5. Set the exit rule: if you act, write down the result and the date that would make you reverse it.
Step 4 has some evidence behind it. In one small-stakes lab study, Sokol-Hessner and colleagues (2009) asked people to see each gamble as one of many, like a trader. Their loss aversion fell, as did their bodily arousal to losses measured by skin conductance. The idea has not been tested on decisions such as a job or a house.
Step 5 matters most for decisions you repeat, where the exit rule has to be set before the result is in. An investor writes the condition for review or exit when buying. A product team fixes the sample size and stopping rule before a test starts and applies it whichever way the early numbers move.
What do I give up if I change and what do I give up if I stay, in the same units over the same period?
Try it now: take one decision you have been avoiding and fill in both columns with the same level of detail.
Where it hurts most
- Housing: Genesove and Mayer (2001) studied Boston condominium sales in the 1990s. Owners whose expected sale price was below what they had paid set asking prices higher by 25 to 35% of that gap. They got somewhat higher prices when they did sell and their flats took longer to sell. Owner-occupants showed about twice the effect of investors. The study controlled for how much equity owners had left, a rival explanation, though other causes cannot be fully ruled out.
- Investing: Odean (1998) studied 10,000 accounts at a US discount broker. Over the full year, investors sold about 14.8% of their gains and 9.8% of their losses. Winners went about one and a half times as readily as losers and the losers they kept went on to do worse than the winners they sold. The pattern fits loss aversion but it has other proposed causes, such as a belief that losers will bounce back.
The uncomfortable version
The losses you avoided are easy to remember. The gains you passed up leave no record, because nothing happened.
Think of the last offer you turned down or the holding you sold at the first dip. Each one felt like protection at the time and no statement you receive will ever show what it cost.
[PULL QUOTE] Your sense of how careful you have been is built from one column only.
There is a second cost that builds over time. Every time you stay put, where you are becomes the new reference point and the next change has to clear the same raised bar.
What are you not doing because it's framed as a loss, even though staying is also a loss?
CogniqOS publishes one cognitive trap per week. Forward this to someone who is weighing whether to stay or switch.
If it landed, restack it.
When it doesn't apply
Extra weight on losses is correct when a loss would end your ability to try again, as when a small firm risks its only large client or a climber pushes on as the weather turns. The errors there are not symmetric: the loss could end your ability to recover, while a missed gain can usually be pursued again. Weighting the loss more is then the correct maths. When the chance you would miss cannot come back, such as an offer that will not be repeated, weigh it as carefully as the loss. Turning down the better option only because its downside feels heavier is the error.
The same rule saves effort in small everyday choices where a careful sum would cost more than the occasional mistake. Carried into a decision you could easily recover from, such as changing a phone contract or a gym membership, the same rule costs you the better option.
Danger zone
Framing Effect + Status Quo Bias + Loss Aversion - whoever sets the reference point decides what counts as a loss and Status Quo Bias makes the current position that reference point by default. Loss Aversion then adds extra weight to every move away from it, which means the same option is accepted or rejected depending on who drew the baseline.
Also a component of Convergence Trap 1: The Escalation Trap → · Also a component of Convergence Trap 8: The Stagnant Strategy →
Also mapped in Cross-Domain Transfer: Military Strategy & Geopolitics → · Also mapped in Cross-Domain Transfer: Medicine & Healthcare → · Also mapped in Cross-Domain Transfer: Product Design & Technology → · Also mapped in Cross-Domain Transfer: Finance & Investing → · Also mapped in Cross-Domain Transfer: Organisational Leadership →

Stress test
1. You have been offered a role that pays 10% more with a six-month probation. Write what you lose by moving and what you lose by staying over the next three years. Which column did you fill in faster?
2. A supplier you have used for five years charges 15% more than a new one with good references. If you were choosing from scratch today, which would you pick?
3. You need cash and hold two funds, one up 30% and one down 20%. Which would you sell if you did not know what you paid for either?
4. What is the worst realistic outcome of the change you are putting off? Could you recover from it within a year?
Testable prediction
If a brokerage hides purchase prices and gains or losses, then over six months the gap between the share of winners and the share of losers its customers sell will be lower than at brokerages that show them. If a pension statement compares the balance with the member's long-run target and not with last year, then switches to cash after a down year will be lower than among members shown the standard statement.
Run this audit with your AI
Paste your decision in, and let your assistant audit it through this bias.
You are my CogniqOS loss reframe. Bias lens: Loss Aversion. Work only with the decision I give you. Do not invent numbers or forecasts. Do not treat a missing number as zero: mark it unknown and say how it affects the call. If you need a fact I have not given, ask for it.

MY DECISION: [paste here]

One decision you're weighing, in a plain sentence - e.g. "Hold the position I'm down on or sell and move on?"

What are my options and what does doing nothing cost? (Required.)

(Optional: the loss I'm trying to avoid.)

If another bias fits better, say so before auditing.

If my input is vague, ask me to sharpen it before auditing.

If it contains more than one decision, make me pick one first.

Audit:

1. Diagnose first: is a possible loss driving this decision? Quote the words in my input that show it.

2. Check the stakes: is the worst case of acting ruinous? If so, treat it as a hard limit and ask how it could be reduced before you continue. If it cannot be undone but would not ruin me, weigh it in the ledger.

3. Two-sided ledger: list what I lose by acting and what I lose by not acting, in the same units and over the same period. Mark every input I have not given you as missing.

4. Wider frame: treat this as one of many similar choices. Which rule would I want to apply to all of them?

5. Exit rule: if I act, what result by what date would make me reverse it?

Return as: the diagnosis + the two-sided ledger + the call (act / stay / insufficient information) + the exit rule.

Keep this in your stack. Next trap in the chain: Status Quo Bias.

Related concepts
- Endowment Effect - Valuing something more once you own it
- Status Quo Bias - The current state becomes the reference point every change is measured against
- Sunk Cost Fallacy - Continuing because stopping would book a loss on what is already spent
- Regret Aversion - Avoiding the choice you would blame yourself for if it went wrong
Also connected in the mapNegativity Bias·Ambiguity Bias·The Default Effect·The Framing Effect·Non-Adaptive Choice Switching (Hot Stove Effect)·Prevention Bias·Zero Risk Bias·The Bottom-Dollar Effect·The Disposition Effect·Sensitivity to Fairness·The Dread Aversion Effect·Risk Premium
Origin
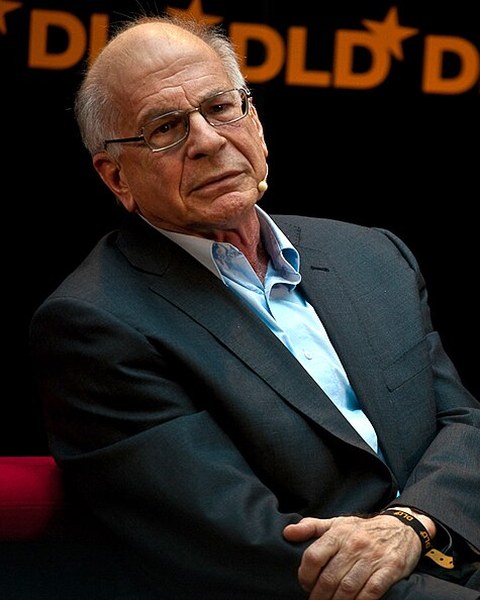 Discovered by, 1979Daniel KahnemanPsychology · Nobel laureate · 1934–2024Proved judgement runs on fast, biased heuristics - the foundation the whole field stands on.See in Origins →
 Discovered byAmos TverskyCognitive psychology · 1937–1996Kahneman's co-author; formalised how people misjudge probability and risk.See in Origins →
Sources
- Kahneman, D. & Tversky, A. (1979). Prospect theory: An analysis of decision under risk. Econometrica 47(2)
- Kahneman, D. (2011). Thinking, Fast and Slow. Farrar, Straus and Giroux
- Brown, A.L., Imai, T., Vieider, F.M. & Camerer, C.F. (2024). Meta-analysis of empirical estimates of loss aversion. Journal of Economic Literature 62(2)
- Gal, D. & Rucker, D.D. (2018). The loss of loss aversion: Will it loom larger than its gain?. Journal of Consumer Psychology 28(3)
- Genesove, D. & Mayer, C. (2001). Loss aversion and seller behavior: Evidence from the housing market. Quarterly Journal of Economics 116(4)
- Odean, T. (1998). Are investors reluctant to realize their losses?. Journal of Finance 53(5)
- Sokol-Hessner, P. et al. (2009). Thinking like a trader selectively reduces individuals' loss aversion. PNAS 106(13)
Read next
Entry #435 of 631 in The Lexicon · see the full Lexicon